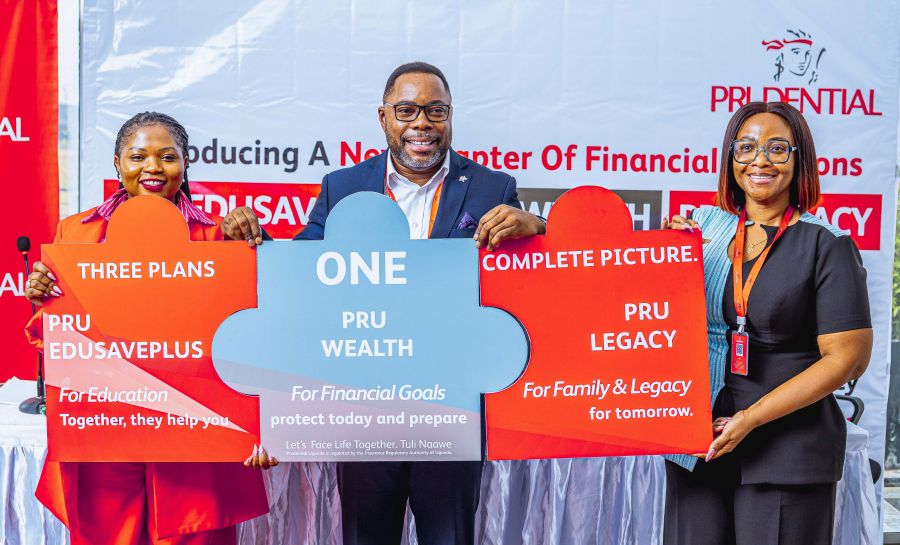
Prudential Uganda is putting financial protection at the centre of its latest push to encourage households to plan for education, wealth creation and unexpected financial shocks.
The insurer says its newly launched Pru Edusave Plus, Pru Wealth and Pru Legacy products are based on a simple premise: saving for a future goal may not be enough if an unexpected event prevents a family from continuing with the plan.
Prudential Uganda Chief Executive Officer Tetteh Ayitevie said the company’s experience in Uganda had shown the importance of combining financial goals with protection.
“Money doesn’t sit free. It always has somewhere it is going. And behind those destinations are people — human beings — and the monetary decisions we make are ultimately about their lives and their future,” Ayitevie said.
He said Ugandan families face a range of long-term financial decisions, particularly around education, wealth accumulation and family security.
“We are a young population, and every child represents a set of financial decisions for a parent or guardian. The question is not simply whether you want your child to go to school. The question is how you make sure the money will be available when that need arrives,” he said.
Ayitevie said Prudential’s approach was to encourage households to use structured financial instruments to prepare for future needs.
“What we do as an insurance company is provide a disciplined approach to handling events in life. We help people put money aside and create a financial structure around the goals they have for themselves and their families,” he said.
The Pru Edusave Plus product allows customers to save towards education over five to 15 years, starting from a monthly premium of shs150,000.
Brenda Nagudi, Prudential Uganda’s Chief Operations Officer, said the product was designed to reflect the different stages of the education journey.
“We know that families don’t have one education expense. There are different milestones — nursery, primary, secondary and university — and each comes with its own financial requirement. This product allows you to plan for those milestones in advance,” Nagudi said.
The product allows customers to select a lump-sum maturity payment or instalment payments aligned with education needs.
Nagudi said the instalment structure could help families plan for education expenses over time rather than relying entirely on one payment at the end of a policy term.
“The idea is to put money aside now so that you can meet the need when it comes. If you know that a child will need funding for secondary school or university in the future, you can structure the plan around those expected milestones,” she said.
The product also provides protection if the premium payer dies or becomes totally and permanently disabled.
According to Prudential’s stated product terms, a qualifying event triggers an immediate benefit equal to 20% of the sum assured, capped at shs10 million, followed by an annual income benefit of 20% of the sum assured, also capped at shs10 million, for the applicable period.
Future premiums are waived under the qualifying conditions, while the policy remains active and matures with 100% of the sum assured plus accrued bonuses, subject to the policy terms.
“The important part is that the financial responsibility for the child’s education does not simply disappear because something has happened to the parent or premium payer. The product is structured to continue supporting the plan under the conditions of the policy,” Nagudi said.
For longer-term financial goals, Prudential has introduced Pru Wealth, with policy terms ranging from eight to 15 years.
The minimum premium is shs250,000, while customers can choose monthly, quarterly, half-yearly or annual payment schedules.
Nagudi said the product was intended for customers who have significant financial goals but need a structured mechanism to work towards them.
“Different generations have different needs. Someone may want to build capital for a business, another person may want to buy or build a home, while another may be planning for education. The common issue is that these goals require money over time, and Pru Wealth provides a framework for planning towards a defined amount,” she said.
Under the product, beneficiaries receive annual income support equivalent to 10% of the sum assured for the applicable period if the policyholder dies, while an additional 100% of the sum assured is payable at maturity, subject to the policy terms.
Ayitevie said the broader objective was to encourage households to think beyond immediate consumption.
“There are certain levels of wealth you cannot create with one salary payment. What we are trying to do is create a platform through discipline for people to get there over time,” he said.
The third product, Pru Legacy, addresses another aspect of financial planning: what happens when a breadwinner remains alive but becomes seriously ill or permanently disabled.
Felicia Manuela Quarshie, Prudential Uganda’s Chief Commercial Officer, said the financial implications of serious illness could extend well beyond medical bills.
“For many households, a serious diagnosis creates two problems at once. There is the medical problem and there is the financial problem. Treatment costs arise, income might be interrupted and savings may have to be used, but household expenses continue,” Quarshie said.
Pru Legacy includes an optional critical illness benefit that pays 50% of the customer’s cover upfront when the applicable conditions are met.
Quarshie said the benefit was designed to address the period when a customer may be dealing with both treatment and the financial consequences of reduced income.
“The money is available while the customer is alive and dealing with the financial impact of serious illness. It is meant to provide financial support at a time when the customer needs to focus on treatment and recovery, while also trying to keep the household financially stable,” she said.
The product also provides protection for permanent total disability under its applicable terms.
For natural death during the policy term, Prudential says 100% of the guaranteed sum assured is paid to beneficiaries, together with a 10% annual family income benefit. Accidental death attracts a benefit of 200% of the applicable cover, according to the company.
Quarshie said the product therefore seeks to broaden the way families think about financial protection.
“Financial planning should consider what happens if you live through a serious health event as well as what happens if you die. Pru Legacy brings those two conversations together,” she said.
Prudential said Pru Legacy is distributed exclusively through its bank partners.
The insurer said partnerships with banks could also make premium payments easier by allowing customers to use established banking relationships and automated payment arrangements.
Ayitevie said the products should be viewed as part of a wider financial plan rather than as substitutes for other forms of saving or investment.
“A life insurance policy is meant to complement the other financial instruments you have. Savings and investments can help generate returns and provide money at the end of a journey, while insurance provides protection against events that can change that journey before it is complete,” he said.
He added that Prudential’s experience paying claims had influenced the revision of its products.
“Over the years, we have spoken to and served many customers, and as we have paid claims through that journey, we have come to appreciate the need to enhance the products we originally brought to the market,” he said.
Prudential said more product developments are expected in the coming months as it continues reviewing its offering based on customer needs and experience in Uganda.
For households considering the products, the insurer said customers should assess their financial goals and affordability and understand the applicable policy conditions before committing to a plan