Pride Bank has partnered with Interswitch Uganda to expand access to banking and payment services through agency banking, automated teller machines (ATMs) and merchant payment points across the country.
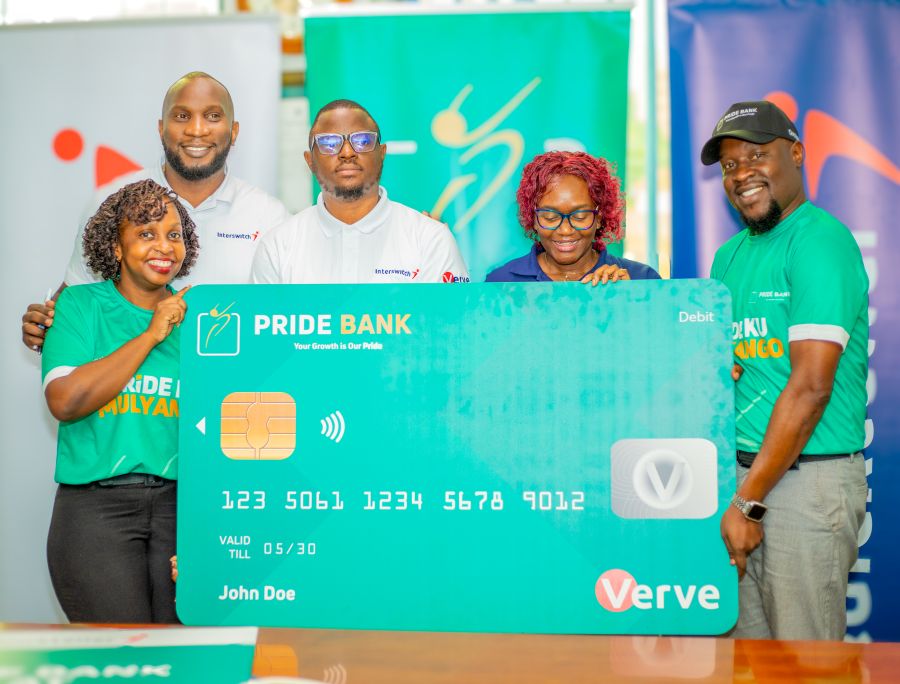
The partnership, officially launched on September 22, 2026, will connect Pride Bank customers to Interswitch’s payment infrastructure through Quickteller Agency Banking and the newly introduced Pride Bank Verve Debit Card.
The initiative is aimed at reducing the need for customers to travel to traditional bank branches to access selected services, particularly for traders, farmers, small business owners and other customers operating away from banking centres.
Speaking at the launch, Moris Seguya, Country General Manager of Interswitch Uganda, said the partnership would enable Pride Bank customers to access a wider payments ecosystem while allowing the bank to extend its services beyond its branch network.
“At Interswitch, we build and run the systems that let money move safely, quickly and reliably,” Seguya said, adding that the partnership would give Pride Bank customers access to Interswitch’s agency, ATM and merchant networks.
Through Quickteller Agency Banking, participating agents will provide selected Pride Bank services, including cash deposits, withdrawals, loan repayments and bill payments.
The arrangement also allows participating businesses to become agency banking points, giving them an opportunity to earn commissions while providing financial services within their communities.
Joseph Fetaa, Head of Business at Pride Bank, said the partnership was designed around the changing needs of customers, who increasingly require banking services that can fit around their businesses and daily activities.
“Our customers are constantly moving. They are running businesses, managing farms, serving clients, travelling, supporting families and pursuing opportunities,” Fetaa said.
He said the partnership would allow Pride Bank to extend its services beyond the traditional banking hall and provide customers with more options for accessing and using their money.
The second component of the partnership is the rollout of the Pride Bank Verve Debit Card.
According to Interswitch, the card will allow Pride Bank customers to transact at Interswitch-enabled ATMs, point-of-sale terminals and supported online merchants.
The card uses EMV Chip and PIN security technology, which is intended to provide additional security for card-based transactions.
The partnership also seeks to address the needs of customers who travel between different parts of the country and may not have convenient access to a Pride Bank branch.
Fetaa said the wider ATM and merchant network would give customers greater flexibility in accessing their money and making payments while away from their usual banking locations.
The initiative is part of Pride Bank’s broader efforts to expand access to financial services and improve customer convenience.
Rather than relying solely on branches, the bank is increasingly using alternative channels to reach customers in communities and trading centres.
For small businesses and traders, the agency banking model could also reduce the time and costs associated with travelling to branches for routine transactions.
At the same time, the participation of local businesses as agents could create additional income opportunities through commissions and increased customer traffic.
Seguya said the partnership reflects Interswitch’s wider objective of using payment infrastructure to support greater access to financial services across Africa.
The launch brings together Pride Bank’s banking services and customer base with Interswitch’s payment infrastructure and acceptance network.
For customers, the immediate changes will include additional locations through which they can access selected banking services, alongside wider options for card-based transactions.
The companies said the partnership will continue to be developed as they seek to expand access, improve customer experience and support innovation in financial services.
The success of the initiative will ultimately depend on the availability of agents and payment points, the reliability of the services and the extent to which customers adopt the new channels.