Financial institutions have been urged to increase lending to agriculture and develop affordable financing products tailored to farmers and agribusinesses to accelerate productivity, strengthen food security and support Uganda’s economic transformation.
aBi Finance Chief Executive Officer Mona Muguma Ssebuliba said agricultural financing should no longer be treated as a peripheral component of financial institutions’ lending portfolios, arguing that the sector requires sustained investment to withstand climate-related shocks and unlock its economic potential.
She made the call during a partners’ engagement meeting hosted by aBi Finance at Kampala Serena Hotel, where the agricultural finance agency reviewed its performance under the 2024–2028 Business Plan, covering implementation from 2024 through the third quarter of 2026.
The meeting brought together financial institutions, development partners and other stakeholders to assess progress in agricultural financing, identify investment gaps and explore ways of expanding access to affordable credit among smallholder farmers and agribusinesses.
Mona said agriculture’s contribution to Uganda’s economy makes it essential for financial institutions to increase their involvement in financing agricultural production, processing, storage and value addition.
She noted that challenges affecting farmers often extend beyond the farm, disrupting traders, processors, exporters, financial institutions and households that depend on agricultural activities.
“One of the clearest lessons this year has offered us is just how interconnected agriculture is with the wider economy. What starts as a problem on a farm moves to the trader, the processor, the exporter, the lender and the household. When agriculture sneezes, the economy catches a cold,” Mona said.
She cited prolonged dry conditions that began in May and affected milk production in parts of Uganda’s cattle corridor, leaving some processors with inadequate milk supplies.
She also pointed to drought and high temperatures in Greater Masaka, Kyotera, Sembabule and Luwero, which affected coffee flowering and bean quality. Uganda’s coffee exports in July were approximately 15 per cent lower than a year earlier, according to figures she presented.
Mona said such developments demonstrate why agricultural financing must increasingly focus on investments that help farmers prepare for and withstand climate-related disruptions.
“We cannot control the weather, but we can influence how well smallholder farmers and agribusinesses withstand it. This means investing in water and feed for the dairy farmer, climate-smart practices for the coffee grower, and storage and processing capacity for the agribusiness. Each of those is an investment, and each depends on finance that reaches the right people at the right time and on the right terms,” she said.
She challenged financial institutions to recognise agriculture as a viable business opportunity and develop lending products that respond to the different needs of farmers, including seasonal production cycles, irrigation requirements and investments in modern agricultural technologies.
Mona said aBi Finance’s 2024–2028 Business Plan was designed to address not only how much financing enters the agricultural sector but also where the money goes, who benefits and the risks it helps to address.
Under the strategy, the agency targets allocating 40 per cent of its financing to women, 30 per cent to young people, five per cent to refugees and 40 per cent to underserved communities, particularly in Northern and Eastern Uganda.
It also aims to dedicate 70 per cent of its financing to green investments by 2028.
She said achieving these objectives would require stronger partnerships with financial institutions capable of translating development priorities into practical lending products.
“These results have not only come from the capital we provide. They come from deliberate choices by our partners, who are offering products tailored to the circumstances of the smallholder farmers and agribusinesses they serve. Our responsibility is to continue supporting them to offer the financial products needed through our lines of credit, agribusiness guarantees and financial services development support,” Mona said.
She warned that despite the progress registered, many farmers and agribusinesses continued to face difficulties accessing the capital required to expand their operations.
“Much as we continue to make progress, the need remains substantial and is further compounded by our tenfold growth ambitions as an economy. Many smallholder farmers and agribusinesses still lack the capital they need. Green finance must reach further, and more financial institutions must come to see agriculture as a core part of their portfolios, not a peripheral one,” she said.
Noah Owomugisha, aBi Finance’s Head of Impact and Sustainability, said the agency was working with financial institutions to address some of the barriers that discourage lenders from extending credit to agriculture.
He explained that aBi Finance operates through three main financial support mechanisms: lines of credit, agribusiness guarantees and capacity-building support.
The lines of credit are intended to address liquidity constraints within financial institutions, enabling them to extend more financing to agricultural clients.
The guarantee facility, meanwhile, provides risk-sharing arrangements to encourage institutions that consider agricultural lending too risky.
Under the arrangement, aBi Finance can compensate participating financial institutions for between 50 and 70 per cent of an outstanding loan in the event of default.
Owomugisha said the mechanism was intended to give lenders greater confidence to finance farmers and agribusinesses that might otherwise struggle to meet conventional lending requirements.
“We are here to ensure that anyone in agribusiness accesses financing conveniently, in a well-structured and sustainable way, and in a manner that meets their investment needs. We do this by working with financial institutions and providing products that address the challenges they face when lending to the agricultural sector,” he said.
He added that capacity-building support was equally important because financial institutions needed the technical knowledge, systems and expertise to assess agricultural investments and manage the risks associated with them.
“Some financial institutions may look at agriculture and conclude that it is too risky to lend to. That is where we come in through the guarantees. We provide an arrangement under which we can compensate the institution between 50 and 70 per cent of the outstanding loan value in the event of default. We also support institutions to build the capacity they need to offer agricultural financing more confidently,” Owomugisha said.
He noted that aBi Finance measured its success not merely by the volume of financing provided but also by the economic, social and environmental changes experienced by beneficiaries.
An impact assessment covering 2024 and 2025 found that 95 per cent of sampled beneficiaries reported increased incomes following access to financing through institutions supported by aBi Finance.
The assessment also established that 71 per cent of respondents had improved or expanded their businesses, while at least 3,000 jobs had been created.
Owomugisha said these findings demonstrated the potential of agricultural financing to transform enterprises and improve livelihoods when credit is appropriately structured and utilised.
Adam Sparre Spliid, Deputy Head of Mission at the Embassy of Denmark in Uganda, also called for stronger participation by financial institutions in financing the transition towards a greener and more sustainable economy.
He said financial institutions had a significant influence on the direction of economic development because their lending and investment decisions determine which businesses expand, which technologies are adopted and which economic activities receive capital.
“Financial institutions do more than mobilise and allocate capital. Their decisions influence which businesses grow, which technologies are adopted, which investments are supported and, ultimately, the kind of economy we build,” Spliid said.
He argued that green finance should be integrated into mainstream financial services rather than treated as a specialised activity, particularly given agriculture’s importance to Uganda’s livelihoods and economic activity.
He said the transition towards sustainable agriculture would require investment in renewable energy, climate-resilient infrastructure, resource-efficient technologies, sustainable production and more efficient agricultural value chains.
Spliid further cautioned that the benefits of green financing should not be restricted to large businesses, saying smallholder farmers, women, young people and small enterprises must also access the opportunities created by the transition.
“The opportunities of a greener economy must extend beyond large enterprises to smallholder farmers, women, young people, small businesses and communities that have traditionally faced barriers to finance. A transition that leaves these groups behind cannot deliver the inclusive economic transformation we seek,” he said.
Drawing from Denmark’s experience, he said sustained cooperation between government, the private sector, research institutions and investors had been instrumental in supporting the country’s transition towards a greener economy.
He encouraged Uganda’s financial institutions to strengthen their capacity, develop appropriate financial products and work with development partners to mobilise investment for sustainable economic activities.
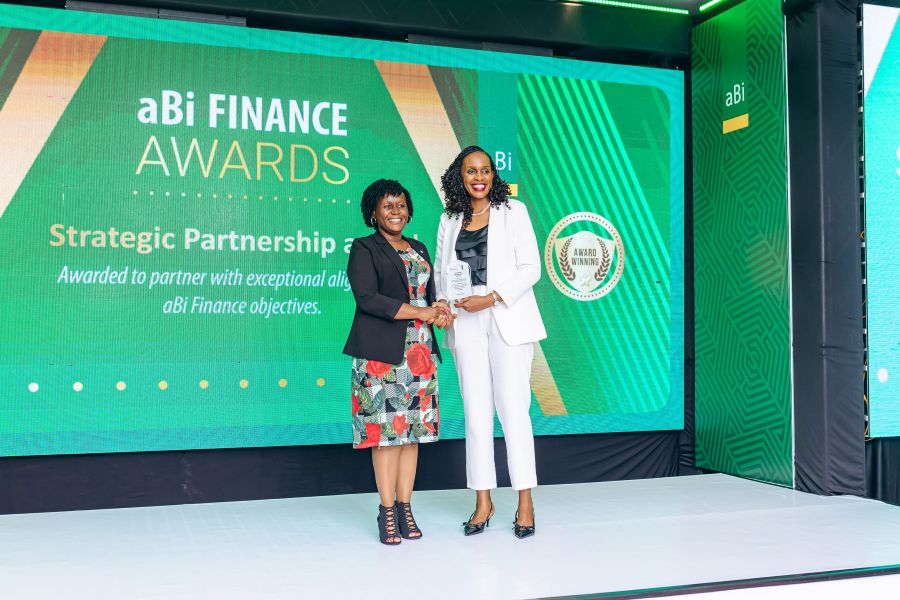
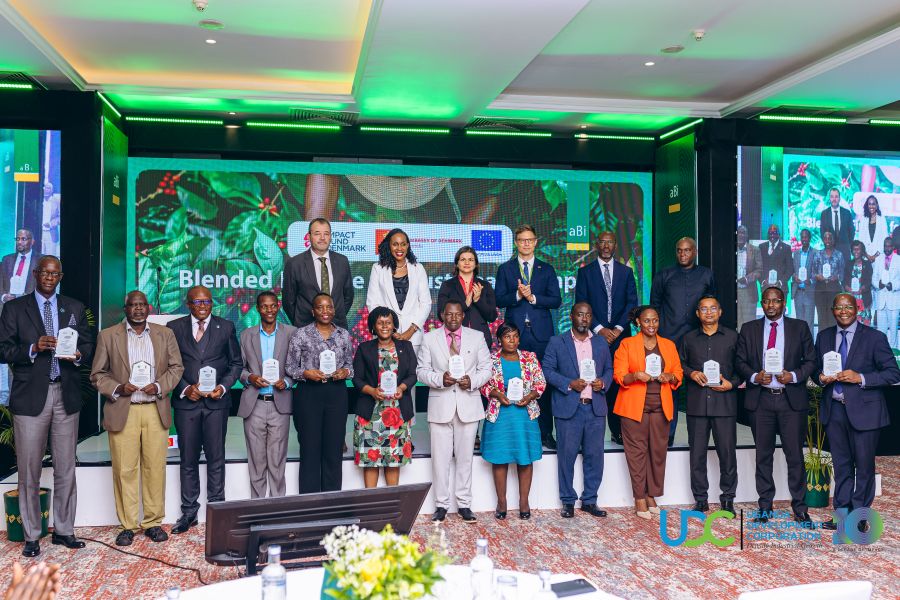
During the engagement, aBi Finance recognised financial institutions that had demonstrated outstanding performance in expanding agricultural credit, promoting green investments and improving access to financial services among underserved groups.
Opportunity Bank was recognised for its exceptional performance in expanding agricultural lending and improving access to inclusive and green finance for Ugandan farmers and agribusinesses.
Centenary Bank was also recognised for its contribution to expanding access to agricultural credit and enabling more farmers and agribusinesses to obtain sustainable financing.
Rural Finance Initiative received the Overall Best Performing Financial Institution Award.
Other recipients included Umoja Microfinance Limited, which won the Access to Green Finance Award; Hofokam Limited, recognised for Green Finance Reporting; and BRAC Uganda Limited, which received the Women’s Finance Excellence Award.
SOLUTI Finance East Africa Limited won the Youth Finance Excellence Award, while UGAFODE Microfinance received the Refugee Finance Excellence Award.
ASA Microfinance Limited was recognised for excellence in expanding financial services in Northern and Eastern Uganda.
The awards were intended to recognise institutions translating agricultural development priorities into practical financial products and services.
As Uganda pursues its tenfold economic growth ambition, aBi Finance says expanding agricultural lending, improving financial inclusion and mobilising investment for climate-resilient production will remain central to its efforts to strengthen the agricultural sector.
Mona said building a sustainable agricultural economy would require financial institutions to move beyond conventional lending approaches and recognise the long-term opportunities available in agriculture.
“A resilient agricultural sector does not happen by chance. It is built through deliberate investment, the right financing and strong partnerships. That is the responsibility we share, and the opportunity before us,” she said.